Field guide
Family money conversations
Many new franchise owners use family funds alongside business money at the beginning. Clear written agreements reduce misunderstandings and tension as your franchise develops.
Why money talk with family gets tricky
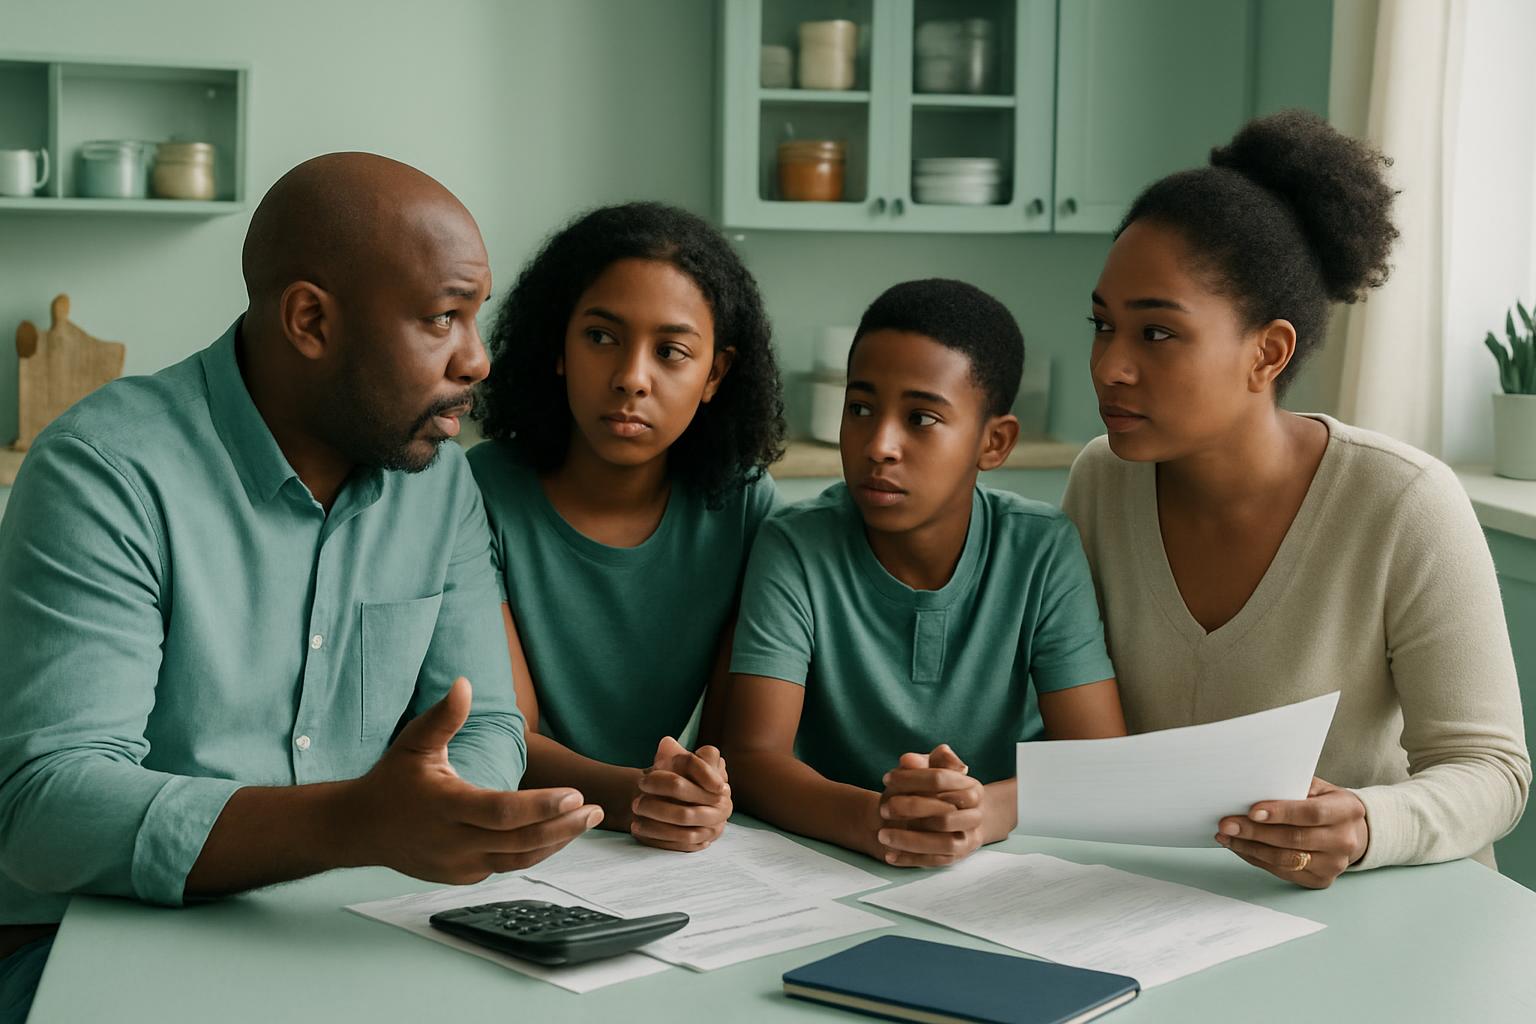
Many new franchise owners in South Africa use joint savings or borrow from relatives to get started. Decisions happen quickly but the lines between family support and business ownership blur once the business is open. Arguments often start when cash is tight or expectations clash.
Without written rules, it is hard to remember who provided which funds, who guarantees which loans, and how income or losses should be shared. Tensions rise if a family member helps with daily work but feels left out of decisions or profit.
Lessons from South African franchise buyers
We see most buyers begin with informal agreements. This can work for the first few months, but the law requires clarity once you sign a franchise agreement or take on staff. If family members are also employees, minimum wage and maximum working hours under the Basic Conditions of Employment Act apply from day one. If a spouse or sibling covers a loan or cash shortfall, SARS may look at the source of working capital.
Section 7 of the Consumer Protection Act gives you 10 business days to cancel a franchise agreement after signing. This window is a chance to settle any money questions with your family. If you later want to formalise roles or investment, it is best to use a written partnership or shareholder agreement, your attorney can draft one based on these early talks.
What one buyer learned the hard way
A buyer in Germiston used a joint family bank account for the first few franchise payments. Two sisters expected their share of profits to match what they put in, but the younger one also ran the shop floor. Arguments started when the business needed extra stock and the sisters disagreed on who should cover the shortfall.
They paused trading and worked with us to list every contribution, draft a simple written plan for handling cash calls and profit splits, and confirm how to handle weekends or public holidays under the legal wage rules. Writing it down helped them keep the shop open and clear up future disputes.
Steps to keep family money clear
Written ground rules make it easier to talk about money, plan ahead, and show SARS or a bank how funds move between home and business. Update the plan if roles or funding change.
- List every financial contribution by person and date
- Agree who covers extra costs, losses or slow months
- Write down how profits or drawings will be shared
- Decide who signs for loans, cards or vendor credit
- Record each person's work hours and duties if family help is paid
- Review your notes before signing the franchise agreement
When to ask us for help
If you are still working out who will invest or backstop the business, or if you are unsure what to put in writing, send us a message with your family money structure. We can help you check which items need legal review and which just need a clear process.
If family members will be employees or loan guarantors, we can point out the wage, tax and contract steps to cover before you sign. By working through our review sessions along with the right field guide, your family is less likely to run into confusion or conflict down the line.
Plan your family money rules
To discuss how funds might shift between your household and the business, describe your circumstances and everyone involved to our team. We will show you where to tighten written agreements.